Keeping Inventory for Small Business: A Practical Guide to Stock Control

Ever found yourself staring at a half-empty shelf wondering where your best-selling product disappeared to? Or maybe you’ve discovered a dusty corner of your storage room filled with items that haven’t moved in months? If these scenarios sound familiar, you’re experiencing the daily reality of managing inventory for your small business. You’re not alone—most small business owners start with passion and product knowledge but soon discover that keeping inventory organized is a completely different skill set.
Why does this matter more than ever? Because in today’s competitive market, your inventory isn’t just products on a shelf—it’s cash sitting in your storeroom. Every item that isn’t moving represents tied-up capital, storage costs, and potential waste. Conversely, every item you run out of represents lost sales and disappointed customers. This balancing act between having enough and having too much is the heart of keeping inventory for small business success.
You’ll discover that effective inventory management isn’t about complex systems or expensive software (though those can help). It’s about creating simple, repeatable processes that give you visibility into what you have, what you need, and what’s costing you money. Whether you’re running a boutique retail store, a small manufacturing operation, or an e-commerce business from your spare room, the principles we’ll explore apply directly to your situation.
Key Takeaways: What You’ll Learn About Small Business Inventory
- You can reduce carrying costs by 20-30% simply by optimizing your inventory levels and avoiding overstock situations
- Small businesses lose an average of $1.75 million annually due to poor inventory management—mostly from stockouts and dead stock
- Implementing basic inventory tracking can increase sales by 10-15% by ensuring popular items are always available
- The right inventory management approach varies dramatically depending on whether you’re selling perishable goods, seasonal items, or high-value products
- Modern tools make professional inventory management accessible to businesses of any size without massive upfront investment
- Regular inventory counts save more than they cost by identifying shrinkage, damage, and obsolescence early
- Your suppliers can become inventory management partners when you establish clear communication and expectations
Understanding Inventory Fundamentals: More Than Just Counting
Before diving into systems and software, let’s establish what we actually mean when we talk about inventory. At its core, inventory represents everything your business owns that’s intended for sale—whether that’s finished products ready to ship, raw materials waiting to be transformed, or partially completed items in production. But here’s where many small business owners get tripped up: inventory isn’t static. It flows through your business like water through pipes, and understanding that flow is key to keeping it under control.
The Inventory Lifecycle: From Arrival to Departure
Every item you stock goes through a predictable journey. It arrives from your supplier (receiving), gets organized and stored (warehousing), moves through your sales process (fulfillment), and finally leaves your business (shipping). Where most systems break down is in tracking that movement accurately. Think about it: if you don’t know exactly when something arrived, where it’s stored, and when it sold, how can you possibly make intelligent decisions about reordering?
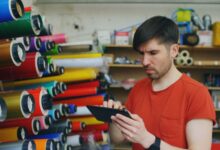
Let’s consider a practical example. Sarah runs a small handmade soap business. She buys olive oil in bulk, creates her soap bars, cures them for four weeks, packages them, and sells them online and at local markets. Her inventory isn’t just finished soap bars—it’s the olive oil waiting to be used, the soap curing on racks, the packaged products ready to ship, and the gift sets she assembles for holiday sales. Each of these stages represents different inventory categories requiring different management approaches.
Editorial Insight: “The biggest mistake I see small businesses make is treating all inventory equally. High-value items need different controls than low-cost consumables. Fast-moving products need different reordering systems than seasonal items. Segmenting your inventory based on value, velocity, and volatility is the first step toward intelligent management.” — Maria Chen, Small Business Operations Consultant
Why Accurate Inventory Counts Matter More Than You Think
You might be wondering: “Can’t I just eyeball it?” For very small operations, maybe. But the moment you have more than a few dozen SKUs or multiple storage locations, guesswork becomes expensive. Inaccurate inventory counts create a ripple effect of problems: you overorder items you already have (tying up cash), underorder items you need (missing sales), and create frustration for yourself and your customers.
The financial impact is real. Consider this: if your inventory accuracy is only 85% (meaning 15% of your counts are wrong), and you have $50,000 in inventory, you’re effectively working with $7,500 worth of “phantom” items—products you think you have but don’t, or products you don’t realize you have. That’s capital you could be investing in marketing, equipment, or growth initiatives.
Choosing Your Inventory Management Approach: From Spreadsheets to Software
Now that we understand why inventory management matters, let’s explore your options. The right approach depends on your business size, complexity, budget, and growth plans. There’s no one-size-fits-all solution, but there is a right fit for your current situation.
| Method | Best For | Key Features | Cost Range | Limitations |
|---|---|---|---|---|
| Manual Spreadsheets | Micro-businesses with <50 SKUs | Total control, no learning curve | Free-$100/year | Error-prone, doesn’t scale |
| Basic Inventory Apps | Small retailers with 50-200 SKUs | Barcode scanning, basic reporting | $15-$50/month | Limited integration options |
| Retail POS Systems | Brick-and-mortar stores | Integrated sales & inventory, customer data | $50-$200/month | Less flexible for non-retail |
| E-commerce Platforms | Online-only businesses | Automatic updates, multi-channel sync | $30-$300/month | Tied to specific sales channels |
| Full ERP Systems | Manufacturing or complex operations | Production planning, advanced analytics | $200-$1,000+/month | Steep learning curve, expensive |
The Spreadsheet Reality Check
Let’s start with the most common starting point: spreadsheets. Many small businesses begin with Excel or Google Sheets because they’re familiar, free (or nearly free), and offer complete control. And for truly tiny operations—think a craft business with 20 products sold at weekend markets—spreadsheets might be perfectly adequate for years.
But spreadsheets have hidden costs. The time spent manually updating quantities after every sale. The inevitable human errors when copying formulas or entering data. The difficulty of getting real-time visibility when you’re away from your computer. Most importantly, spreadsheets don’t “talk” to other systems. Your sales don’t automatically deduct from inventory counts, and your reordering doesn’t happen automatically when stock gets low.
If you’re using spreadsheets, here’s a pro tip: create a dedicated inventory sheet with these columns: SKU, Product Name, Location, Current Quantity, Minimum Quantity (reorder point), Maximum Quantity, Supplier, Cost, and Last Count Date. Update it religiously after every inventory movement. Set up conditional formatting to highlight items below minimum quantity in red. It’s basic, but it’s systematic.
When to Graduate to Dedicated Software
How do you know when it’s time to move beyond spreadsheets? Watch for these signs:
- You’re spending more than 2-3 hours per week on inventory updates and reconciliation
- You’ve had multiple instances of selling items you didn’t actually have in stock
- You’re expanding to multiple sales channels (online store plus physical location)
- Your product catalog has grown beyond what you can easily track mentally
- You’re hiring employees who need inventory access without spreadsheet training
The transition doesn’t need to be traumatic. Many inventory management solutions offer free trials, and most can import your existing spreadsheet data. The key is choosing software that matches your workflow rather than forcing you to adapt to its limitations.
Practical Inventory Management Techniques That Actually Work
Whether you’re using spreadsheets or sophisticated software, certain techniques dramatically improve your inventory control. These aren’t theoretical concepts—they’re practical methods used by successful small businesses every day.
The ABC Analysis: Focusing on What Matters Most
Not all inventory deserves equal attention. The 80/20 rule applies here too: roughly 20% of your products generate 80% of your revenue. ABC analysis helps you identify which items fall into which category:
- A Items (Top 20%): High-value products that contribute most to revenue. These need frequent monitoring, tight control, and safety stock.
- B Items (Middle 30%): Moderate value products. These require standard management and periodic review.
- C Items (Bottom 50%): Low-value items that contribute little to revenue but might be necessary. These can be managed with simple systems and bulk ordering.
Here’s why this matters: if you’re spending equal time counting $100 items and $1 items, you’re wasting precious resources. By categorizing your inventory, you can apply appropriate controls to each category. For instance, you might count A items weekly, B items monthly, and C items quarterly. You might keep higher safety stock for A items while implementing just-in-time ordering for C items.
Setting Intelligent Reorder Points
One of the most common questions about keeping inventory for small business is: “When should I reorder?” The answer isn’t “when you’re running low”—that’s already too late. The answer is mathematical: Reorder Point = (Average Daily Sales × Lead Time) + Safety Stock.
Let’s break that down with an example. Suppose you sell an average of 5 units per day of a popular product. Your supplier takes 7 days to deliver after you order. That’s 35 units (5 × 7) you’ll sell during the lead time. But what if you have a busy week and sell 8 per day? That’s 56 units during lead time. To avoid stockouts, you add safety stock—maybe 20 units. So your reorder point becomes: (5 × 7) + 20 = 55 units.
When your inventory drops to 55 units, you place a new order. By the time you receive it (7 days later), you’ll ideally have around 20 units left (your safety stock). This simple calculation prevents both stockouts and excessive inventory buildup.
Regular Cycle Counting vs. Annual Physical Inventory
Traditional businesses often do a complete physical inventory once a year—shutting down operations, counting everything, and reconciling discrepancies. For small businesses, this approach is incredibly disruptive and often inaccurate due to fatigue and time pressure.
A better approach is cycle counting: regularly counting a small subset of inventory so everything gets counted multiple times per year. You might count your A items weekly, B items monthly, and C items quarterly. This spreads the work throughout the year, minimizes disruption, and catches errors quickly when they’re easier to trace.
The key to successful cycle counting is consistency. Schedule it like any other important business task. Use a checklist. Investigate discrepancies immediately (was it sold? damaged? stolen? mis-shelved?). Update your records on the spot. Over time, you’ll achieve much higher accuracy with much less stress.
Deep Dive: Popular Small Business Inventory Solutions
Let’s examine three popular approaches to keeping inventory that work particularly well for different small business scenarios.
Square for Retail: All-in-One Simplicity
If you run a physical retail store, Square offers an integrated solution that combines point-of-sale, inventory management, and basic analytics. What makes it compelling for small businesses is its simplicity—the inventory features work seamlessly with the sales system. When you sell an item, inventory deducts automatically. When you receive a shipment, you can update quantities right from the vendor invoice.
Square shines for businesses with relatively straightforward inventory needs. The barcode scanning works well, the low stock alerts are helpful, and the reporting gives you visibility into what’s selling and what’s not. The limitation comes if you have complex inventory needs like manufacturing, assembly, or lot tracking. But for most small retailers, it strikes the right balance between capability and complexity.
TradeGecko (Now QuickBooks Commerce): E-commerce Powerhouse
For businesses selling primarily online—especially across multiple channels like Shopify, Amazon, and eBay—TradeGecko (now part of QuickBooks Commerce) offers robust multi-channel inventory synchronization. The magic happens automatically: when an item sells on any connected channel, inventory updates everywhere.
This is particularly valuable for preventing overselling, which damages customer relationships and creates logistical headaches. The system also handles purchase orders, vendor management, and basic warehouse operations. The learning curve is steeper than simpler solutions, but the automation pays dividends for growing e-commerce businesses. The main limitation is cost—it’s priced for businesses serious about scaling their online presence.
Zoho Inventory: The Flexible Middle Ground
Zoho Inventory sits in the sweet spot between simple apps and complex enterprise systems. It’s particularly well-suited for small businesses that both sell and fulfill orders—think manufacturers, distributors, or businesses doing custom assembly.
Where Zoho excels is in workflow flexibility. You can set up multiple warehouses, manage drop shipping, handle bundles and kits, and integrate with accounting software. The interface is clean without being simplistic. Pricing is reasonable, especially for businesses with moderate order volumes. The downside? The abundance of features can be overwhelming initially, and some advanced capabilities require higher-tier plans.
Common Inventory Mistakes That Cost Small Businesses Money
Even with the best intentions, small business owners often make predictable errors in inventory management. Recognizing these pitfalls is the first step toward avoiding them.
- Flying Blind Without Regular Counts: Assuming your records are accurate because your system says so. Inventory discrepancies accumulate silently until they create major problems. Regular counting—even if just spot checks—keeps you honest.
- Treating Dead Stock as “Maybe It’ll Sell”: Holding onto slow-moving inventory for months or years, tying up capital and storage space. Establish clear rules: if something hasn’t sold in X months (typically 6-12), discount it heavily, bundle it, or donate it for the tax write-off.
- Overordering Based on Emotion, Not Data: Loading up on a product because you “have a good feeling” or because the supplier offered a discount. Unless you have historical data showing consistent demand, emotional ordering leads to cash flow problems.
- Neglecting Supplier Relationships: Viewing suppliers as adversaries rather than partners. Good suppliers can offer better terms, faster turnaround, and valuable market intelligence. Communicate your needs clearly and pay on time.
- Ignoring Seasonality in Planning: Using the same reorder points year-round when demand fluctuates seasonally. Analyze historical sales patterns and adjust inventory levels accordingly. Build up before peak seasons, draw down afterward.
- Failing to Account for Shrinkage: Assuming all inventory loss is from sales. Theft, damage, and administrative errors typically account for 1-3% of inventory value. Build this into your calculations and investigate unusual patterns.
Frequently Asked Questions About Small Business Inventory
How often should I do physical inventory counts?
It depends entirely on your business size and complexity, but here’s a practical framework. If you’re just starting out with fewer than 100 SKUs, a monthly full count might be manageable and valuable. As you grow, transition to cycle counting: count your highest-value items weekly, medium-value items monthly, and low-value items quarterly. The key is consistency—whatever schedule you choose, stick to it. Regular counts catch errors when they’re small and traceable, rather than discovering major discrepancies during year-end accounting.
Remember that inventory accuracy isn’t about perfection—it’s about being close enough to make good business decisions. If your counts are within 1-2% of your records consistently, you’re doing well. If discrepancies regularly exceed 5%, you need more frequent counting or better tracking systems.
What’s the simplest way to start tracking inventory?
Start with a spreadsheet and discipline. Create a simple template with columns for product name, SKU, current quantity, location, cost, and selling price. Update it immediately after every sale, purchase, or adjustment. Yes, it’s manual. Yes, it takes time. But it forces you to pay attention to inventory movements, which is the foundation of good management.
Once you’ve maintained consistent spreadsheet tracking for a month, you’ll understand what information matters to your business. Then you can evaluate software solutions with clarity about what features you actually need versus what sounds nice. Too many small businesses buy expensive software only to use 10% of its capabilities because they never established basic discipline first.
How much inventory should I keep on hand?
This is the million-dollar question, literally. The answer balances several factors: your sales velocity, supplier lead times, storage costs, and cash flow constraints. A good starting formula is: Ideal Inventory Level = (Average Monthly Sales × 2) + Safety Stock. The “× 2” assumes you want roughly two months of sales coverage, which provides buffer for supplier delays or demand spikes.
But here’s the nuance: this formula should vary by product category. Fast-moving essentials might warrant 4-6 weeks of coverage. Seasonal items might need buildup before peak seasons and drawdown afterward. Slow-moving or experimental items might justify just 2-4 weeks of coverage. The goal isn’t a single number for everything—it’s intelligent segmentation based on each item’s characteristics.
Can I manage inventory without expensive software?
Absolutely. Many successful small businesses manage inventory effectively with spreadsheets, basic apps, or even paper systems for years. The tool matters less than the process. What you need is consistency in recording movements, regularity in counting, and discipline in reordering.
That said, there comes a point where manual management consumes more time than it saves. When you’re spending hours weekly on inventory tasks that could be automated, when errors are becoming frequent, or when you’re missing sales due to stockouts despite your efforts—that’s when software becomes worth the investment. Think of it as hiring a digital assistant that never sleeps, never makes calculation errors, and gives you instant visibility into your stock levels.
What inventory metrics should I track regularly?
Focus on these five key metrics initially: Inventory Turnover Ratio (cost of goods sold ÷ average inventory), Days Inventory Outstanding (365 ÷ turnover ratio), Stockout Rate (percentage of time items are unavailable when wanted), Carrying Cost Rate (storage, insurance, obsolescence costs as percentage of inventory value), and Order Accuracy (percentage of orders filled correctly from available stock).
These metrics tell different stories. Turnover ratio shows how efficiently you’re converting inventory into sales. Days inventory outstanding reveals how long items sit before selling. Stockout rate indicates missed sales opportunities. Carrying costs highlight storage efficiency. Order accuracy reflects operational effectiveness. Track them monthly initially, then quarterly as patterns emerge. They’ll guide your inventory decisions more effectively than gut feelings ever could.
How do I handle inventory for seasonal businesses?
Seasonal inventory management requires anticipation and discipline. Start by analyzing at least two years of sales data to identify clear patterns. Build inventory gradually before your peak season—don’t wait until the last minute when suppliers might be overwhelmed. During the season, monitor sales daily and adjust reorders dynamically. As the season ends, implement aggressive markdowns on remaining seasonal items to convert them back to cash.
The post-season analysis is crucial. What sold well? What didn’t? What pricing strategies worked? Document these insights while they’re fresh. Then create a seasonal inventory plan for next year based on actual data rather than memory. Consider consignment arrangements or flexible return policies with suppliers for truly unpredictable seasonal items. The goal is to maximize sales during the peak while minimizing leftover inventory afterward.
Conclusion: Turning Inventory from Burden to Advantage
Keeping inventory for your small business doesn’t need to be a constant source of stress. By implementing systematic approaches tailored to your specific needs, you transform inventory from a necessary evil into a competitive advantage. The visibility you gain allows smarter purchasing decisions. The control you establish prevents costly stockouts and overstock situations. The cash flow improvements directly boost your bottom line.
Start small but start today. Pick one area—whether it’s implementing regular counts, setting reorder points, or simply creating accurate records—and master it. Then build from there. Your inventory system should grow with your business, evolving from simple tracking to sophisticated management as your needs change. Remember that the goal isn’t perfection; it’s continuous improvement. Every step toward better inventory control is a step toward a more profitable, sustainable business that serves your customers reliably while freeing you to focus on growth rather than guesswork.